Mahama: Africa’s Youth Need Affordable Finance to Build Businesses
Ghanaian President John Dramani Mahama says access to affordable, long-term financing is essential if young Africans are to build businesses, create jobs and drive the continent’s industrial growth.
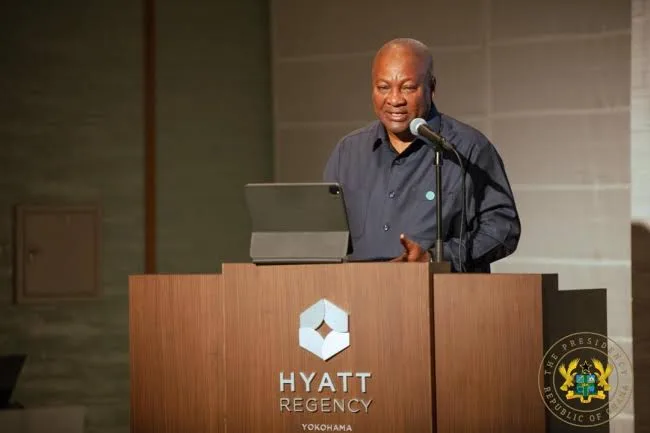
Ghanaian President John Dramani Mahama has called for African governments and financial institutions to make affordable funding more accessible to young entrepreneurs, warning that limited access to capital continues to hold back business growth, industrialization and job creation across the continent.
Speaking at the Africa Trade Summit 2026 in Accra on January 28, Mahama argued that Africa’s economic transformation would remain difficult to achieve if small businesses and entrepreneurs could not secure financing on terms they could realistically repay. He said access to long-term capital remained particularly constrained for small and medium-sized enterprises, which play a significant role in Africa’s industrial workforce.
The president’s message centres on a challenge familiar to young business owners across Africa: having a viable idea does not necessarily mean having the money to turn it into a sustainable enterprise. Entrepreneurs often need funding to purchase equipment, secure premises, hire staff, acquire inventory and expand into new markets. When borrowing costs are high or lenders demand substantial collateral, many struggle to move beyond small-scale operations.
Mahama argued that African economies must move beyond dependence on exporting raw materials and importing finished products. Developing local manufacturing, processing agricultural produce and expanding indigenous businesses, he said, would help create employment and retain more economic value within the continent.
His position reflects a broader debate over how African countries can finance growth while creating opportunities for a rapidly expanding young population. Without greater access to capital, young people with entrepreneurial ambitions risk remaining trapped in informal, low-productivity activities even when their businesses have the potential to grow.
The scale of the challenge is reflected in Ghana’s labour market. A Ghana News Agency feature published in September, citing Ghana Statistical Service figures, reported that unemployment among people aged 15 to 35 averaged 21.9 per cent during the first three quarters of 2025, compared with a national unemployment rate of 12.8 per cent. The report also said nearly two million young people were not in employment, education or training by the third quarter of that year.
These figures help explain why access to business finance has become an important part of the discussion about youth employment. Not every young person will become an entrepreneur, and affordable loans alone cannot solve unemployment. But businesses that can obtain capital, reach customers and operate sustainably may be better positioned to hire workers and contribute to local economic activity.
Mahama has previously outlined plans to reduce borrowing costs through credit-system reforms and blended finance, which combines funding from different sources to make certain investments more viable. At the Kwahu Business Forum in April 2025, he also announced plans for a national venture capital fund to support businesses led by young people and women, alongside reforms intended to encourage financial institutions to lend to productive sectors.
There are also practical efforts to widen access to funding. In August 2026, Consolidated Bank Ghana and the Social Investment Fund signed an agreement to disburse $5 million to women-led, youth-led and other micro, small and medium-sized enterprises under a programme designed to expand access to finance and support job creation. The initiative combines funding with business-development support and financial literacy.
Such programmes could help address financing barriers, but their long-term impact will depend on how funds are distributed, the cost of borrowing, repayment conditions and whether businesses receive the support needed to survive beyond their early stages. Entrepreneurs also need dependable electricity, transport infrastructure, stable economic conditions and access to markets. Credit can help a business grow, but it cannot compensate for every weakness in the operating environment.
Mahama has also called for African governments to mobilize more domestic investment. At the Africa Trade Summit, he pointed to pension funds, insurance companies and sovereign wealth funds as potential sources of long-term capital, provided appropriate investment structures and safeguards are established. He also advocated stronger development finance institutions to help mobilize private investment for industrial projects.
The proposal raises an important question about how African capital is deployed. If more funding can be channelled into productive businesses, infrastructure and manufacturing, it could help local enterprises expand without relying exclusively on expensive commercial loans or foreign investment. However, pension and insurance funds must still protect the interests of the people whose savings they manage, making sound regulation and careful risk assessment essential.
For young entrepreneurs, the real test will be whether these policy commitments translate into accessible funding with reasonable repayment terms, transparent application processes and support beyond the initial loan. Governments must also ensure that financing reaches businesses outside major cities and extends to entrepreneurs who may lack established banking relationships.
Mahama’s call ultimately goes beyond helping young people start businesses. It is about giving African enterprises a realistic chance to grow, employ others and compete in regional and international markets. With millions of young people seeking productive work, affordable finance could become a powerful tool for economic transformation, but only if it is matched by sound institutions, practical business support and policies that allow enterprises to thrive. The continent’s challenge is not simply to encourage young people to dream bigger, but to build a financial system that gives viable ideas a fair chance of becoming sustainable businesses.
More on Africa
Africa
Formula 1 Returns to Africa After 33 Years With Historic Rwanda Grand Prix Deal
13 Oct 2026
Africa
Nigeria–South Africa Tensions Rise as Fani-Kayode Issues Strong Warning
13 Sept 2026
Africa
South Africa Reverses Asylum Policy After Vehicles Burned and Foreign-Owned Shops Looted
10 Oct 2026
Africa
Kenya’s Ruto Tours Dangote Refinery Ahead of Lamu Refinery Launch
26 Sept 2026
Africa
Sadio Mané Launches $20 Million Mango Agro-Processing Project in Senegal
22 Sept 2026
You may also like
Africa
Multi-Car Crash Kills 21 in South Africa’s Western Cape
14 Sept 2026
Africa
Business Forum 2026: Mauritius Pitches Itself as Africa’s Financial Bridge
13 Sept 2026
Africa
After Immigration Panic, Kenya Offers 90 Days for Foreign Businesses to Comply
10 Sept 2026
Africa
Former Sierra Leone President Koroma Returns Home Under Nigerian Escort
6 Sept 2026
Africa
ECOWAS Swears In Five Judges as Faye Calls for Stronger Public Trust in Regional Justice
7 Oct 2026
Africa
Ethiopia, Eritrea Break Diplomatic Ties as Tigray Fighting Escalates
2 Oct 2026